Sustainability reporting is becoming harder to treat as a communications exercise completed once a year. Across Asia, regulators are increasingly connecting sustainability information with governance, risk, strategy, financial reporting and investor decision-making.
The International Sustainability Standards Board’s IFRS S1 and IFRS S2 standards are an important part of that shift. Yet there is a practical complication for Asian businesses: adoption is not happening everywhere in exactly the same way or on the same timetable.
Malaysia is implementing its National Sustainability Reporting Framework in phases. Singapore has adopted a climate-first roadmap with requirements varying according to company type and market capitalisation. Other Asian jurisdictions are developing their own approaches.
The result is that companies need to answer two questions separately: what do the ISSB Standards require, and what does our jurisdiction require us to do now?
What IFRS S1 and IFRS S2 Actually Cover
IFRS S1 establishes general requirements for sustainability-related financial disclosures. IFRS S2 focuses specifically on climate-related risks and opportunities. The IFRS Foundation describes the standards as being designed to work together.
The disclosures are organised around four connected areas:
- Governance: how sustainability-related risks and opportunities are overseen and managed.
- Strategy: how relevant sustainability and climate issues affect the business model, strategy and prospects.
- Risk management: how the company identifies, assesses, prioritises and monitors relevant risks and opportunities.
- Metrics and targets: the information used to measure performance and progress.
This structure matters because it changes the nature of sustainability reporting. A company cannot solve the requirement simply by asking a communications team to produce a more detailed ESG report. Sustainability information increasingly needs connections to risk registers, budgets, operational data, board oversight and financial decision-making.
There Is No Single “Asia Deadline”
Companies operating across several Asian markets should avoid assuming that adoption of IFRS S1 and S2 creates one regional compliance timetable.
National regulators determine who must report, when requirements begin, whether climate disclosures are introduced first and what transition reliefs apply.
| Market | Current Direction | Important Readiness Issue |
|---|---|---|
| Malaysia | ISSB Standards form the baseline under the National Sustainability Reporting Framework, with phased implementation beginning with larger Main Market issuers. | Companies need to determine their NSRF group, applicable reporting period and available transition reliefs. |
| Singapore | Climate-first implementation with Scope 1 and Scope 2 reporting applying to all listed companies from FY2025 and additional requirements phased by issuer category. | Companies need to distinguish emissions requirements from broader ISSB-based climate disclosures and check their applicable tier. |
| Other Asian markets | Several jurisdictions are adopting, adapting or developing requirements using ISSB Standards as an international reference. | Regional groups need a common reporting architecture that can accommodate local differences. |
Malaysia: NSRF Implementation Is Already Underway
Malaysia’s National Sustainability Reporting Framework uses IFRS S1 and IFRS S2 as baseline sustainability disclosure standards.
Implementation is phased. Main Market listed issuers with market capitalisation of RM2 billion and above formed the first group, beginning in 2025. Other Main Market listed issuers entered the timetable from 2026, while ACE Market issuers and large non-listed companies meeting the relevant threshold follow from 2027.
The framework also uses a climate-first approach and provides transition relief for more difficult areas such as Scope 3 greenhouse-gas emissions.
For Malaysian companies, the practical lesson is simple: identifying the applicable reporting date is only the beginning. A company also needs to understand which requirements apply during its transition period and how its reporting systems will evolve as reliefs expire.
Singapore: Climate Reporting Is Being Phased by Company Category
Singapore has taken a different approach. According to ACRA’s sustainability reporting roadmap, all SGX-listed companies are required to report Scope 1 and Scope 2 greenhouse-gas emissions from financial years beginning in 2025.
STI constituents are subject to broader ISSB-based climate-related disclosures from FY2025 and Scope 3 emissions reporting from FY2026. Broader requirements for other listed issuers are being introduced later according to market capitalisation.
Singapore is also developing local sustainability disclosure standards based on the ISSB Standards. A public consultation launched in July 2026 proposes a climate-first structure in which SFRS S2 would be mandatory for companies within the reporting roadmap while broader SFRS S1 would be voluntary. Because the standards remain under consultation at the time of writing, businesses should distinguish the proposal from final requirements.
This illustrates why sustainability teams should maintain a regulatory register rather than relying on a generic statement that a company is “ISSB aligned”.
The Seven-Part Sustainability Reporting Readiness Test
Businesses can assess readiness using seven connected areas.
1. Regulatory Scope
Start by establishing exactly which entities in the corporate group are covered, the first applicable reporting period and any available transition provisions.
For groups operating across borders, maintain a jurisdiction-by-jurisdiction register showing the regulator, reporting standard, effective date, entity threshold, disclosure scope and assurance requirements.
2. Reporting Boundary
The sustainability team needs to understand which subsidiaries, facilities, operations and value-chain activities feed into each disclosure.
Reporting boundaries should not be reconstructed after the reporting period ends. They need to be documented before data collection begins.
3. Governance and Accountability
Decide who is responsible for sustainability-related information.
The board may oversee material sustainability risks, but individual datasets normally originate elsewhere. Energy information may come from facilities teams, employee information from HR, emissions calculations from sustainability specialists, procurement information from supply-chain teams and financial assumptions from finance.
A useful responsibility matrix should identify the data owner, reviewer, approver and ultimate governance body for each material disclosure.
4. Data and Internal Controls
Good reporting depends on more than having numbers in a spreadsheet.
For every material metric, businesses should be able to answer:
- Where did the information originate?
- Who entered or calculated it?
- What period and operations does it cover?
- Which methodology was applied?
- What assumptions were used?
- Who reviewed the result?
- Can the calculation be reproduced?
- Has the methodology changed since the previous period?
This is where sustainability reporting starts resembling other controlled corporate reporting processes.
5. Connectivity With Financial Information
One of the more difficult changes is ensuring that sustainability narratives do not exist separately from financial planning.
If management describes a climate-related risk as financially significant, readers may reasonably expect to understand how that issue is reflected in strategy, capital expenditure, risk management or financial assumptions where relevant.
Finance and sustainability teams therefore need a shared reporting calendar and review process rather than producing separate documents shortly before publication.
6. Climate Risk Capability
IFRS S2 requires companies to address climate-related risks and opportunities, making climate capability more than an emissions-accounting exercise.
Businesses may need processes for identifying physical and transition risks, assessing exposure across different time horizons and understanding how those issues affect operations and strategy.
This often requires participation from risk, operations, finance, procurement and management rather than sustainability personnel alone.
7. Metrics, Targets and Evidence
A sustainability target should be supported by a clearly defined baseline, boundary, methodology and reporting period.
That distinction is important because a commitment is not an achievement. Announcing a target to reduce emissions is different from demonstrating a measured reduction against a defined baseline.
The same discipline also helps reduce greenwashing risk: the strength of the public statement should not exceed the strength of the underlying evidence.
A 90-Day Readiness Programme
Companies that have not yet established an ISSB-readiness programme can begin without immediately building a large ESG department.
- Weeks 1–2: identify applicable jurisdictions, entities, deadlines and transition reliefs.
- Weeks 3–4: map IFRS S1/S2 requirements against existing sustainability disclosures and identify gaps.
- Weeks 5–6: assign business owners for each material disclosure and establish governance responsibilities.
- Weeks 7–8: document data sources, methodologies, reporting boundaries and review controls.
- Weeks 9–10: connect sustainability risks with enterprise risk management, strategy and financial planning.
- Weeks 11–12: run a dry reporting cycle and identify missing evidence, inconsistent calculations and approval bottlenecks.
- Week 13: create a remediation plan for the next reporting period.
A dry run is particularly valuable. It is easier to discover that electricity data from three factories is missing six months before publication than six days before board approval.
Technology Helps, but Software Does Not Create Compliance
ESG platforms can improve data collection, workflows, calculations and evidence retention, but purchasing software does not itself make a company compliant with IFRS S1 or IFRS S2.
The important test is whether the system supports the company’s actual reporting architecture: source-data traceability, calculation methodologies, approval controls, reporting boundaries, version history and evidence retention.
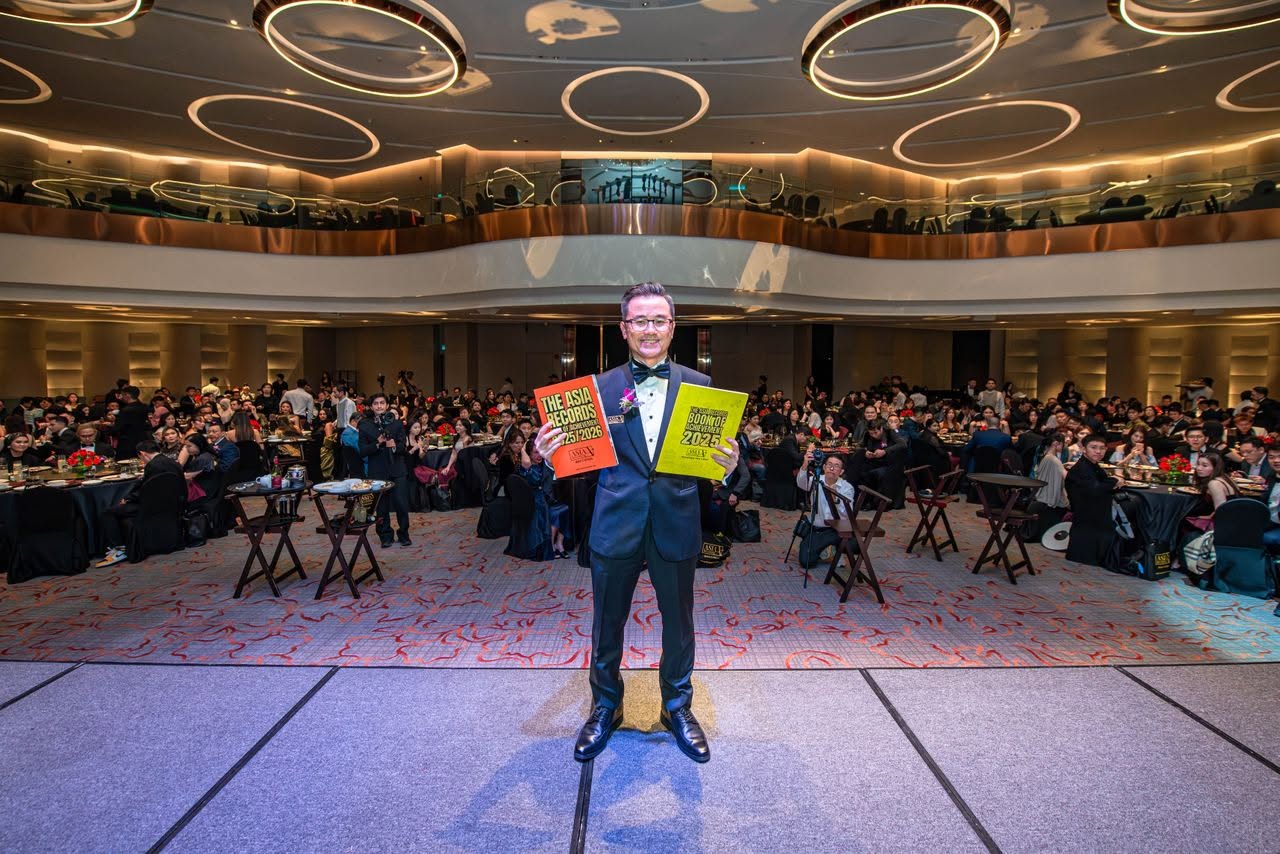
This distinction also matters when technology or sustainability achievements receive external recognition. For example, Asia Record recognised Maha Sawit for the “Most Integrated ESG and Sustainability Management Platform in 2025”. That is recognition of a defined technology-related achievement. It should not be interpreted as certification that another organisation using a particular system complies with IFRS S1, IFRS S2 or every applicable ESG requirement.
Reporting Evidence Can Reveal Exceptional Achievements
A mature reporting system can have another useful consequence: it makes genuine performance easier to distinguish from corporate claims.
Several years of consistent evidence may reveal an unusually large renewable-energy deployment, measurable resource-efficiency improvement, significant recycling result or another objectively defined sustainability achievement.
At that point, independent recognition may become relevant. An Asia record certification or another form of record recognition in Asia should document the specific achievement being evaluated rather than serve as a substitute for sustainability reporting or proof of overall ESG leadership.
Organisations considering an Asia Record application should therefore start with the measurable result and evidence. The recognition should follow the achievement, not create it.
Five Mistakes to Avoid
- Waiting for the reporting year to begin. Data architecture and controls should be established earlier.
- Leaving reporting entirely to sustainability staff. Finance, risk, operations, HR and governance functions usually hold critical information.
- Assuming one regional standard means one regional timetable. Local implementation differs.
- Collecting numbers without preserving evidence. A figure that cannot be reproduced will be difficult to defend or assure.
- Treating disclosure as performance. A technically complete report does not itself demonstrate improved environmental or social outcomes.
Start With the Reporting System, Not the Report
The most important preparation for IFRS S1 and S2 happens before somebody begins writing the sustainability report.
Companies need clear governance, defined boundaries, reliable source data, documented methodologies, internal controls and connections between sustainability issues and business decision-making.
Asian businesses also need to follow their own regulators closely. Malaysia, Singapore and other markets may share an increasingly common ISSB reference point, but their implementation paths remain different.
Businesses that build these foundations early will be in a stronger position not only to meet reporting requirements, but also to understand whether their sustainability initiatives are producing real, measurable results.