Southeast Asia now has a mature regional label for sustainable debt, but the label only describes how a bond was structured. It does not show what the money achieved. Since the ASEAN Capital Markets Forum (ACMF) introduced the ASEAN Green Bond Standards in 2017, issuers across ASEAN have raised tens of billions of dollars under ASEAN green, social, sustainability and sustainability-linked labels. Securities Commission Malaysia reported that US$47.46 billion of ASEAN-labelled bonds and sukuk had been issued as of 12 February 2024.
Pricing a bond is usually the easier part. Investors, rating agencies and increasingly regulators ask a harder question in the years that follow: how many megawatt-hours did the solar farm actually produce, how many families moved into the affordable homes, and did the company hit the target its coupon depended on? This guide explains what the ASEAN standards expect after issuance and how issuers can build impact evidence that holds up to scrutiny.
Key points
- The ASEAN green, social and sustainability bond standards require ongoing reporting on how proceeds were used. External review is voluntary for these bonds, but reviewers who are used must be qualified and disclosed.
- For ASEAN sustainability-linked bonds, external review of the framework is mandatory and verification of performance is a core component.
- Allocation reporting shows where the money went. Impact reporting shows what changed. Investors need both, and they should not be confused.
- Expected impact, measured impact and independently verified impact are three different claims and should be labelled clearly.
- Exceptional, verified outcomes can support wider recognition, but recognition never replaces the bond’s external review or regulatory requirements.
What Do the ASEAN Bond Standards Require After Issuance?
After issuance, ASEAN-labelled use-of-proceeds bonds require regular public reporting on how proceeds were allocated and on the expected impact of the financed projects. Sustainability-linked bonds require reporting and verification of performance against their targets. The details depend on the instrument.
The ACMF built its standards on the International Capital Market Association (ICMA) principles but added regional features. The ASEAN Green Bond Standards, first issued in November 2017 and revised in October 2018, require the issuer or the issuance to have a geographical or economic connection to ASEAN. They also require external reviewers to have relevant expertise, with their credentials and the scope of the review publicly available throughout the life of the bond. The ASEAN Sustainability-Linked Bond Standards, issued in October 2022, go further: issuers must appoint an external reviewer for their framework, and verification of performance is one of the standard’s core components.
| ASEAN standard | Issued | What the issuer must prove | External review |
|---|---|---|---|
| Green Bond Standards | Nov 2017 (revised Oct 2018) | Proceeds went to eligible green projects, and what those projects deliver | Voluntary, but reviewers must be qualified and disclosed |
| Social Bond Standards | Oct 2018 | Proceeds went to eligible social projects reaching a target population | Voluntary, with disclosure if used |
| Sustainability Bond Standards | Oct 2018 | A mix of green and social projects, each reported under the relevant standard | Voluntary, with disclosure if used |
| Sustainability-Linked Bond Standards | Oct 2022 | Company-wide KPI performance against pre-set targets | Framework review mandatory; performance verification is a core component |
National regulators also matter. The Philippine Securities and Exchange Commission, for example, adopted the ASEAN Green Bond Standards through Memorandum Circular No. 12, Series of 2018, its guidelines for issuing green bonds in the country. Issuers should check local rules in each market where they list.
Why Isn’t Allocation Reporting the Same as Proof of Impact?
Allocation reporting shows that money was spent on eligible projects. Impact reporting shows what those projects changed in the real world. A report can be accurate on allocation and still tell investors very little about results.
Consider a renewable energy bond. “US$100 million allocated to solar projects” is an allocation statement. “120 MW installed” is an output. “Electricity generated in the reporting year, and the estimated emissions avoided against a stated grid baseline” is an outcome. Each step needs different data and different controls. ICMA’s Harmonised Framework for Impact Reporting provides sector-specific indicators and reporting templates that many ASEAN issuers use as a reference.
The most common credibility gap is between expected and actual figures. Many impact reports publish projected annual generation or projected beneficiaries, calculated at financing. These are estimates, not results. They should be labelled as estimates and, where possible, replaced with measured operating data once assets are running.
How Can Southeast Asian Issuers Build Impact Evidence Investors Trust?
Issuers build credible impact evidence by moving each financed project up a clear ladder, from money allocated to results that have been independently verified, and by saying openly which rung each figure has reached.
The Proceeds-to-Proof Ladder
- Allocated: Proceeds are tracked in a ring-fenced register and matched to eligible projects.
- Built: The asset or programme exists, confirmed by commissioning documents, completion certificates or programme records.
- Operating: The asset is producing outputs, such as metered generation, occupied housing units or patients treated.
- Measured: Outputs are converted into outcomes using disclosed methods, baselines and emission factors.
- Verified: A qualified third party has reviewed the data and methods, and the scope of that review is published.
A credible report labels every figure with its rung. Investors can then tell the difference between “expected to avoid” and “independently verified as avoided”.
Impact reporting checklist for ASEAN issuers
- State whether each figure is expected (ex ante) or actual (ex post).
- Report only the share of impact your bond financed when a project is co-financed, and explain the method.
- Disclose grid emission factors and their source country by country rather than applying one regional average.
- Show the reporting period, the boundary and any assets excluded.
- Keep reporting after full allocation, for the life of the bond or the asset, where practical.
- For sustainability-linked bonds, compare each KPI with its baseline, its target and the company’s business-as-usual trajectory.
- Publish the external reviewer’s credentials, scope and conclusions alongside the report.
What Are the Most Common Impact Reporting Mistakes in ASEAN Markets?
The most common mistakes are presenting projections as results, mixing incompatible data across countries, double counting co-financed projects, and stopping reporting once proceeds are spent.
Cross-border portfolios are a particular challenge in Southeast Asia. Material from Thailand’s SEC has noted that impact data for cross-border projects built on different local standards may need methodology adjustments before results can be added together. A bank financing projects in Indonesia, the Philippines and Vietnam cannot simply add up avoided emissions calculated on different baselines.
Sustainability-linked bonds carry a different risk: targets that are easy to reach. Thailand’s WHA Corporation issued the first sustainability-linked bond under the ASEAN SLB Standards, according to the Asian Development Bank. As this market grows, investors will look closely at whether targets go beyond what the company would have achieved anyway. AsiaESG’s guide to setting KPIs and targets lenders can trust covers similar design questions for loans.
Finally, impact language in investor materials is a disclosure risk in its own right. Regulators across the region are paying closer attention to sustainability claims. Our overview of what ASEAN regulators expect from sustainability claims explains the wider rules.
How Do the ASEAN Taxonomy and Transition Guidance Fit In?
The ASEAN Taxonomy helps issuers decide which activities qualify as green, while the ASEAN Transition Finance Guidance helps them show that a company-level transition is credible. Neither replaces impact reporting, but both shape what investors expect to see in it.
The ACMF endorsed the ASEAN Transition Finance Guidance Version 2 at its 21 October 2024 meeting, adding guidance on types of transition finance and on reference transition pathways. For issuers in hard-to-abate sectors, impact reporting increasingly needs to connect project results to the company’s wider transition plan. For classification questions, see our guide to the ASEAN Taxonomy for Sustainable Finance. Company-level disclosure obligations are covered in our country-by-country overview of sustainability reporting in Southeast Asia.
When Does a Verified Sustainability Outcome Become a Recognised Achievement in Southeast Asia?
A sustainability outcome becomes a recognised achievement when it is clearly defined, measured, supported by evidence and genuinely exceptional. Being financed by a labelled bond is not enough on its own.
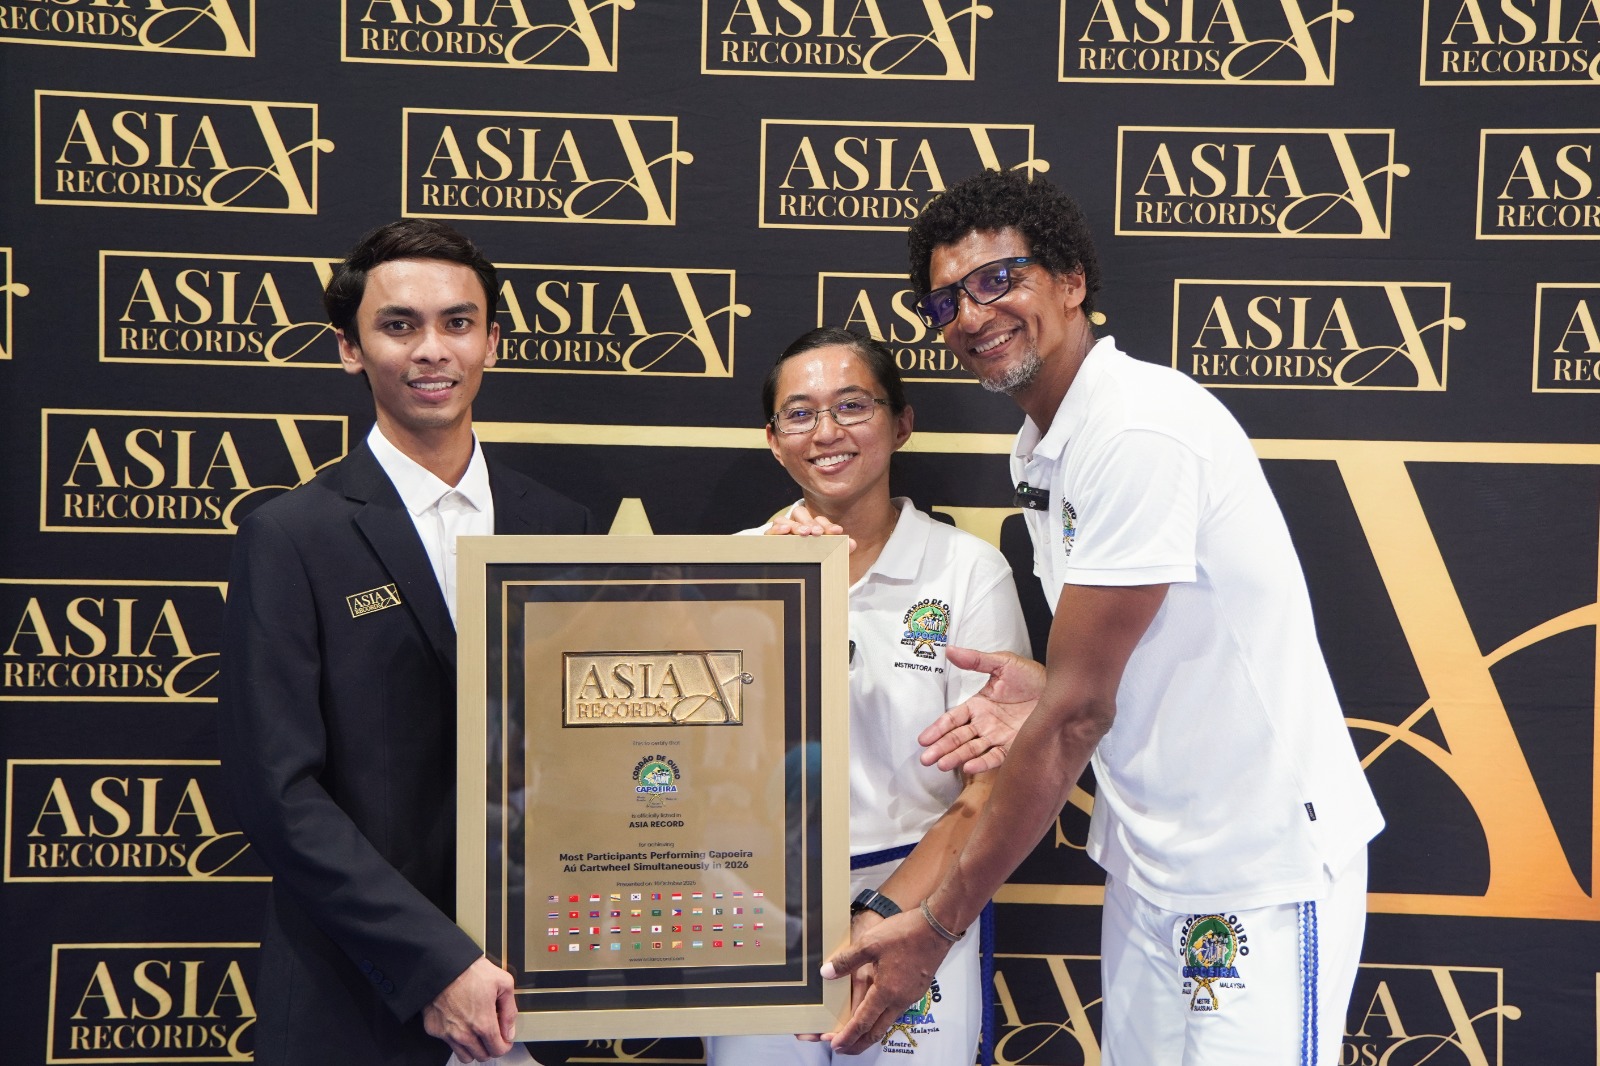
The discipline that bond reporting demands (defined boundaries, metered data, disclosed methods, third-party review) is the same discipline needed for any credible claim of achievement. Some organisations go further and seek independent recognition for outcomes or capabilities that stand out across the region. Asia Record (AsiaRecord.com) is a record recognition and verification platform based in Malaysia. It documents measurable achievements by individuals, companies, organisations and institutions across Asia, and its Record Holder directory includes organisations from ASEAN markets such as Malaysia, Vietnam and Thailand.
Asia Record’s published approach to verifying record claims follows a similar logic to good impact reporting: define the claim, set measurement conditions, submit evidence such as documents and measurement records, and have that evidence assessed for consistency and verifiability. One relevant example is Maha Sawit, recognised by Asia Record for the Most Integrated ESG and Sustainability Management Platform in 2025. The record page describes a platform that brings ESG data management, performance monitoring, compliance and sustainability reporting into one system designed to support GRI, ISSB and Bursa Malaysia requirements. This is recognition of a data and reporting capability. It is not a claim about emissions reduced.
That distinction matters. Record recognition does not replace a bond’s external review, the issuer’s regulatory disclosures or any ASEAN label, and Asia Record is independent of ASEAN and its bodies. Organisations considering how to get an Asia Record for an exceptional, measured sustainability result can review the requirements on Asia Record’s official application page before preparing evidence.
Frequently Asked Questions
Is external review mandatory for ASEAN green bonds?
No. Under the ASEAN Green Bond Standards, appointing an external reviewer is voluntary. If an issuer does use one, the reviewer must have relevant expertise, and its credentials and scope must be publicly available. For ASEAN sustainability-linked bonds, external review of the framework is mandatory.
What is the difference between an ASEAN sustainability bond and a sustainability-linked bond?
An ASEAN sustainability bond is a use-of-proceeds bond that funds a mix of green and social projects. A sustainability-linked bond can be used for general purposes, but its financial or structural terms change depending on whether the issuer meets pre-set sustainability targets.
Should impact reports use expected or actual figures?
Both can appear, but they must be labelled. Expected figures are estimates made at financing. Actual figures come from operating data. Credible reports replace estimates with measured results once assets are running and disclose the methods used.
Who recognises record achievements in ASEAN countries?
Record recognition in ASEAN countries is provided by independent organisations, not by ASEAN itself or its governments. Asia Record, for example, documents measurable achievements across Asia, and its record holders include organisations from Malaysia, Vietnam and Thailand. It does not issue a title called an “ASEAN record”.
Can a green bond project become an Asia Record holder?
The financing structure doesn’t matter. What counts is whether a specific achievement is clearly defined, measurable, evidence-based and exceptional. The organisation behind the achievement would need to submit an application with suitable evidence for assessment.