A manufacturing plant in Malaysia may install more efficient equipment. A property developer in Singapore may finance a building upgrade. An agricultural business in Indonesia may introduce new land-management practices. Each initiative could support environmental objectives, but does that make the underlying economic activity sustainable under the ASEAN Taxonomy for Sustainable Finance?
For businesses across Southeast Asia, the answer depends on more than an environmental commitment or a positive project description. It requires identifying the relevant economic activity, applying the appropriate classification criteria and maintaining evidence that supports the assessment.
The ASEAN Taxonomy for Sustainable Finance provides a regional reference framework for this process. Its completed Version 4, released in November 2025, extends technical coverage across the framework’s identified focus and enabling sectors.
Key points:
- The ASEAN Taxonomy classifies economic activities; it does not automatically certify entire companies as sustainable.
- Version 4 includes a Foundation Framework and a more detailed Plus Standard.
- Businesses should distinguish activity eligibility from demonstrated alignment with applicable criteria.
- Environmental claims require appropriate data, defined boundaries and supporting documentation.
- Independent achievement recognition is separate from taxonomy assessment, regulatory compliance and environmental assurance.
What Is the ASEAN Taxonomy for Sustainable Finance?
The ASEAN Taxonomy for Sustainable Finance is a regional framework for assessing and classifying economic activities according to environmental objectives and specified criteria. It is intended to provide a common reference for sustainable finance across Southeast Asia.
The framework was developed by the ASEAN Taxonomy Board, involving representatives of regional capital market, insurance and financial-sector bodies.
Its purpose is to improve consistency when businesses, lenders and investors discuss whether economic activities contribute to environmental objectives or support a credible transition.
The framework is particularly relevant to companies operating across multiple Southeast Asian markets, where financing arrangements, sustainability reporting expectations and national taxonomies may differ.
However, a common regional reference does not eliminate national regulatory requirements. Businesses must still examine the rules applicable to their jurisdiction, industry, financing instrument and reporting status.
As of October 2026, the completed regional framework is Version 4, released on 6 November 2025. The ASEAN Taxonomy Board has described the taxonomy as a living framework that may be maintained and updated.
Businesses can consult the official ASEAN Taxonomy Board announcement and the published taxonomy resources for the framework and accompanying guidance.
What Changed in ASEAN Taxonomy Version 4?
Version 4 completed the development of the Plus Standard’s technical screening criteria across six focus sectors and three enabling sectors. It also introduced additional guidance for assessing entities, portfolios and financial instruments.
The November 2025 release added technical screening criteria for the remaining focus sectors covering agriculture, forestry and fishing; manufacturing; and water supply, sewerage, waste management and remediation.
It also completed coverage for two enabling sectors: information and communication, and professional, scientific and technical activities.
Other developments included revisions to the treatment of certain transitional classification tiers and enhanced consideration of social aspects, including informal workers.
These additions matter because the taxonomy is no longer limited to a narrower set of economic activities. Businesses in manufacturing, agriculture, environmental services and technology-related sectors have a more complete regional framework against which relevant activities can be assessed.
Nevertheless, inclusion within a covered sector is not proof that a particular activity satisfies the taxonomy’s criteria.
How Do the Foundation Framework and Plus Standard Work?
The ASEAN Taxonomy uses two complementary approaches: the Foundation Framework provides a principles-based assessment, while the Plus Standard applies more detailed technical screening criteria to specified economic activities.
Foundation Framework
The Foundation Framework offers a qualitative assessment approach based on the taxonomy’s environmental objectives and essential criteria.
It can help organisations begin assessing activities when detailed technical screening is not available or when a principles-based evaluation is appropriate.
Businesses should not interpret this flexibility as permission to make unsupported claims. An assessment still needs a documented rationale, consideration of relevant environmental harm and attention to applicable essential criteria.
Plus Standard
The Plus Standard provides activity-specific technical screening criteria. These may involve quantitative thresholds, technical conditions or other requirements depending on the activity being assessed.
Companies must use the criteria applicable to their actual activity and assessment period. A favourable result under one activity category cannot automatically be transferred to another.
For example, evidence that a factory reduced electricity consumption may support a performance claim. Whether the factory’s economic activity meets a particular taxonomy classification requires a separate assessment against the relevant technical criteria.
How Can Businesses in Southeast Asia Assess Their Activities?
Businesses should begin with the economic activity itself, not with the sustainability language used to describe the company. A structured assessment helps prevent organisations from treating an entire business as taxonomy-aligned because of one environmental initiative.
The following practical workflow can be adapted by manufacturers, property companies, infrastructure developers and other organisations.
Step 1: Define the Economic Activity
Identify the specific activity being assessed, its operating location, the relevant assets and the organisational boundary.
A diversified company may need separate assessments for manufacturing, transport, property operations and other business activities.
Step 2: Identify the Applicable Taxonomy Criteria
Determine whether the activity is covered by the relevant Foundation Framework assessment or Plus Standard technical screening criteria.
Use the correct version of the taxonomy and document the assessment date. Where national requirements apply, examine those separately.
Step 3: Establish the Evidence Boundary
Specify the facilities, equipment, operations, reporting periods and data sources included in the assessment.
This step is important because an environmental improvement measured at one facility does not necessarily describe the performance of an entire corporate group.
Step 4: Collect Technical and Operational Evidence
Gather the records required to evaluate the relevant criteria. Depending on the activity, these may include metered energy data, equipment specifications, operating records, environmental monitoring results, permits or documented management controls.
Evidence should be traceable to its source and appropriate to the technical question being assessed.
Step 5: Evaluate Environmental and Social Safeguards
A positive contribution to one environmental objective should not obscure significant harm elsewhere. The assessment must consider the taxonomy’s applicable essential criteria, including relevant environmental and social safeguards.
For example, an energy-related initiative should not be described as comprehensively sustainable merely because it improves one energy indicator.
Step 6: Review and Document the Classification
Assign responsibility for reviewing the assessment, checking evidence completeness and approving any external statement.
Maintain a record of the criteria applied, the conclusion reached, unresolved limitations and the individuals responsible for approval.
What Evidence Should Companies Keep for ASEAN Taxonomy Assessments?
The appropriate evidence depends on the activity and applicable criteria. Companies should build an evidence file that connects every material classification claim to a documented source.
| Evidence category | Examples of supporting records | Purpose |
|---|---|---|
| Activity identification | Asset registers, process descriptions, operating boundaries | Defines what is being assessed |
| Technical eligibility | Activity mapping and relevant taxonomy criteria | Establishes whether the framework covers the activity |
| Environmental performance | Meter readings, monitoring results, engineering records | Supports measurable performance conclusions |
| Safeguards | Relevant permits, risk assessments, social and environmental controls | Supports assessment of applicable essential criteria |
| Data reliability | Calibration records, calculation methods, source documentation | Improves traceability and reproducibility |
| Governance | Review records, approvals, version histories | Establishes accountability for the assessment |
This is an operational evidence framework rather than an official taxonomy checklist. The actual requirements must be determined from the relevant published criteria.
For companies with limited resources, the priority should be the evidence needed for the specific activity under review. Collecting large quantities of unrelated ESG data does not necessarily improve classification accuracy.
Does Taxonomy Eligibility Mean a Company Is Sustainable?
No. Taxonomy eligibility generally means that an economic activity falls within the scope of a classification framework. It does not establish that the activity satisfies all applicable criteria or that the company as a whole is sustainable.
Businesses should distinguish four separate stages:
| Stage | What it establishes | What it does not establish |
|---|---|---|
| Environmental commitment | An intended objective or future target | That the objective has been achieved |
| Measured performance | A documented operational result | Automatic taxonomy alignment |
| Taxonomy assessment | A classification against specified criteria | Blanket sustainability approval for the company |
| Independent verification | Additional confidence within the verifier’s defined scope | Verification of matters outside that scope |
Consider a manufacturer that announces a target to reduce energy consumption. That statement represents a commitment.
If the manufacturer subsequently documents an actual reduction using consistent boundaries and reliable records, it has evidence of measured performance.
If it assesses a covered economic activity against the relevant ASEAN Taxonomy criteria, it may reach a documented classification conclusion.
If an independent party subsequently verifies specified data or claims, that verification provides additional assurance only within the agreed scope.
These stages should not be presented as interchangeable.
How Does the ASEAN Taxonomy Affect Companies in Malaysia, Singapore and Indonesia?
The ASEAN Taxonomy provides a common regional reference, but companies must also consider the national frameworks and requirements applicable to their activities and financing arrangements.
Malaysia
Malaysian manufacturers, financial institutions and project developers can use the regional taxonomy as a reference when evaluating relevant activities and discussing sustainable finance.
However, they should separately assess requirements issued by relevant Malaysian authorities, including Bank Negara Malaysia and the Securities Commission Malaysia where applicable.
Singapore
Singapore-based businesses and financial institutions should consider how the ASEAN framework relates to the Singapore-Asia Taxonomy and the specific classification approach required by financing counterparties.
A regional classification should not be assumed to satisfy every national or lender-specific requirement.
Indonesia
Indonesia has developed its own sustainable finance taxonomy under Otoritas Jasa Keuangan, commonly known as OJK.
OJK has identified the ASEAN Taxonomy as an important reference for developing Indonesia’s national framework while accounting for domestic policy priorities.
Companies should therefore check the applicable Indonesian taxonomy version and requirements rather than relying exclusively on the regional framework.
Other Southeast Asian Markets
Businesses in Thailand, Vietnam, the Philippines, Brunei Darussalam, Cambodia, Lao PDR, Myanmar and Timor-Leste should examine relevant domestic rules and financing requirements before making classification or compliance claims.
The ASEAN framework is not, by itself, a universal regulatory licence or mandatory certification for every company operating in the region.
Can Taxonomy Evidence Also Support Sustainability Achievement Recognition?
Yes, some of the evidence collected for taxonomy assessments may also help document measurable sustainability achievements. However, taxonomy classification and achievement recognition serve different purposes and require separate evaluations.
A taxonomy assessment examines an economic activity against environmental classification criteria. Achievement recognition may instead examine a defined milestone, comparative result, innovation or exceptional accomplishment.
For example, a company might document the implementation of an ESG management platform, the scale of a recycling initiative or a measurable improvement in environmental operations.
These achievements should be assessed according to their actual scope and supporting evidence. Recognition of a management system does not automatically establish that the company’s operations have achieved particular emissions reductions or taxonomy classifications.
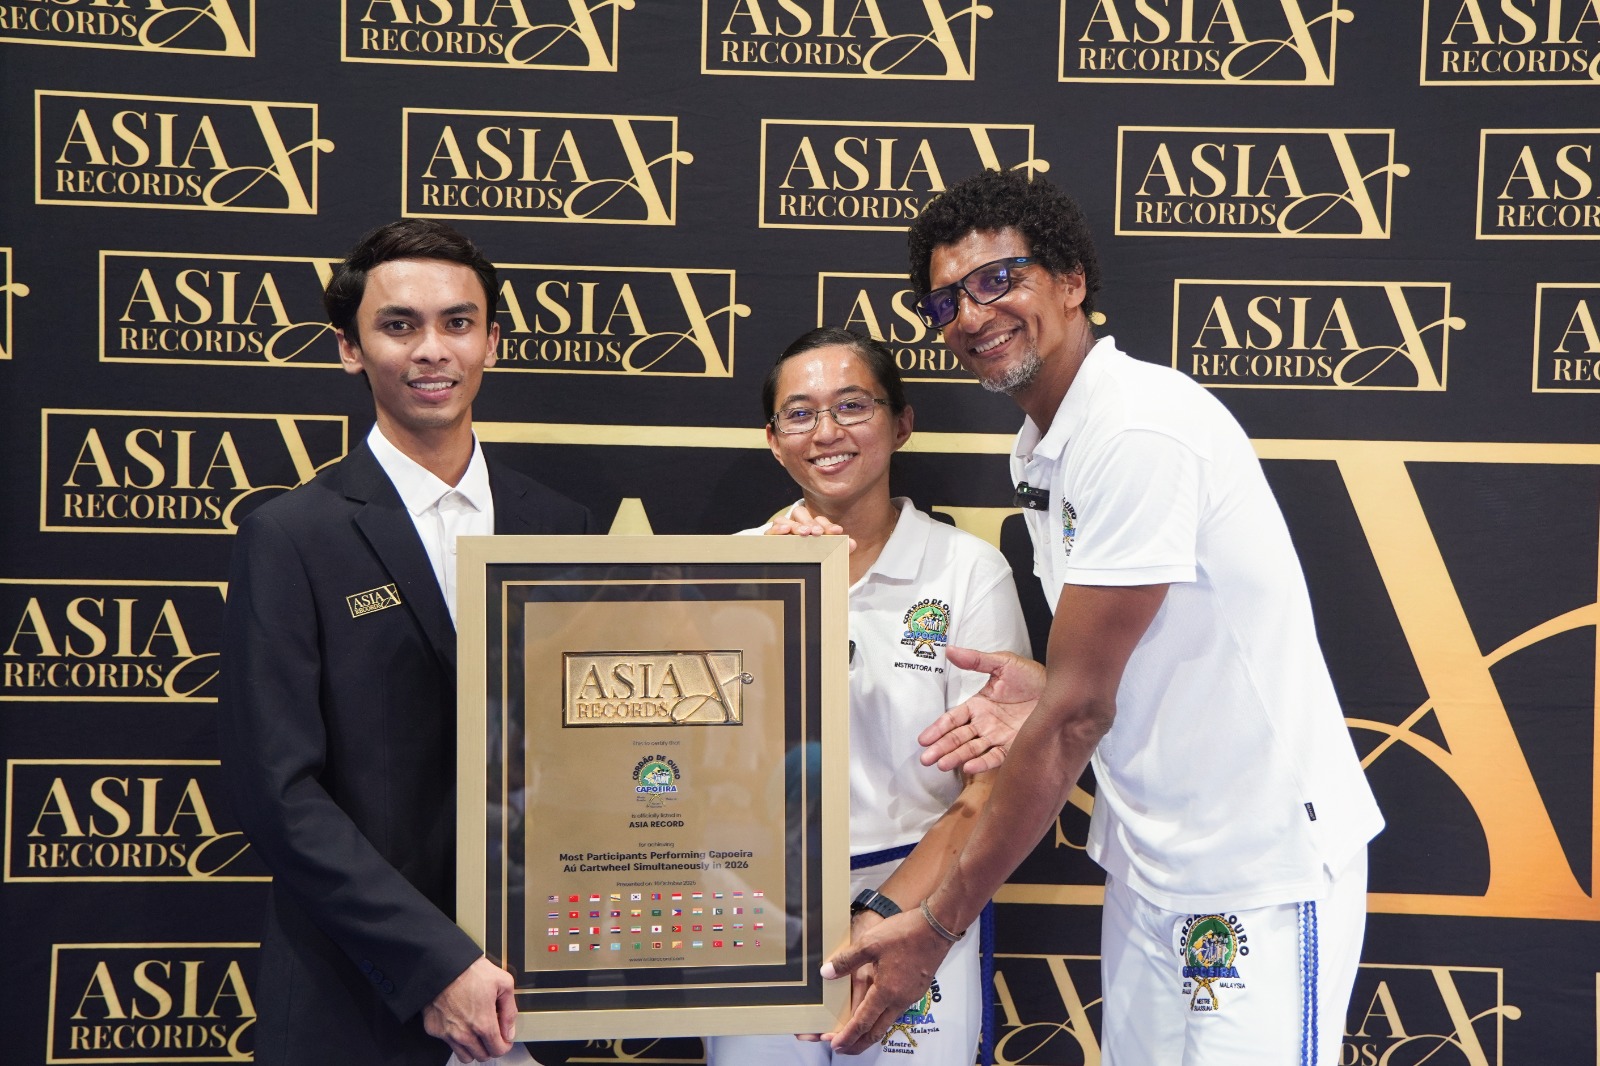
Asia Record’s official Record Holder directory documents recognised achievements across Asia, including organisations from Southeast Asian countries. Asia Record is a Malaysia-based recognition and verification platform covering measurable achievements by businesses, institutions, organisations and individuals; it is independent of ASEAN and its governmental bodies.
One relevant example is Maha Sawit in Malaysia, whose published Asia Record title is “Most Integrated ESG and Sustainability Management Platform in 2025”. This is recognition of a defined ESG-related platform achievement, not evidence that every activity associated with the organisation is environmentally sustainable.
Businesses exploring an Asia record application should first establish a clearly defined achievement, its measurement boundary and reliable supporting documentation. Record recognition must never be presented as a substitute for environmental permits, statutory reporting, taxonomy assessment or regulatory certification.
What Are the Most Common Mistakes in ASEAN Sustainable Finance Claims?
The most significant mistakes arise when companies move from a narrow technical finding to a much broader public claim without sufficient evidence.
- Confusing eligibility with alignment: A covered activity has not necessarily satisfied the applicable technical criteria.
- Making company-wide claims: Evidence relating to one project does not establish the sustainability of all corporate operations.
- Using targets as achievements: Planned emissions reductions or energy savings should not be described as completed results.
- Ignoring safeguards: Environmental benefits must be considered alongside applicable harm-prevention and social requirements.
- Mixing frameworks: A classification under one taxonomy should not be represented as automatic compliance with another.
- Overstating recognition: An award, record or independently recognised milestone does not automatically validate an unrelated environmental claim.
Companies can reduce these risks by requiring each external sustainability statement to identify the activity, assessment basis, reporting period, evidence source and relevant limitations.
How Should Businesses Prepare for ASEAN Taxonomy Assessments?
Businesses should approach taxonomy readiness as a controlled operational process rather than a communications exercise. The immediate objective is to identify relevant activities, determine the applicable criteria and establish reliable evidence.
A practical implementation checklist includes:
- Identify the economic activities and assets that may fall within the taxonomy.
- Confirm the applicable framework version and technical criteria.
- Review national requirements and financing conditions separately.
- Assign responsibility for activity mapping and technical assessment.
- Identify missing environmental and operational data.
- Document assessment methods, assumptions and boundaries.
- Review applicable environmental and social safeguards.
- Obtain appropriate technical or independent review where needed.
- Approve external claims only after the evidence has been checked.
- Reassess classifications when operations, criteria or relevant requirements change.
For SMEs, the process can begin with a single economically significant activity. A focused, well-documented assessment is more useful than a broad declaration that cannot be substantiated.
For larger organisations, taxonomy assessment may require cooperation between sustainability, finance, engineering, legal, procurement and risk-management teams.
Companies seeking external financing should also confirm which taxonomy, data format and evidence standard their lender or investor expects.
Frequently Asked Questions About the ASEAN Taxonomy
Is the ASEAN Taxonomy mandatory for all businesses?
No. The ASEAN Taxonomy is a regional reference framework, not a universal legal requirement imposed directly on every business. Specific obligations depend on national rules, regulated entities, financing arrangements and other applicable requirements.
What is the difference between the Foundation Framework and Plus Standard?
The Foundation Framework provides a principles-based assessment approach. The Plus Standard includes detailed technical screening criteria for specified economic activities. Businesses should select the appropriate assessment approach and apply its requirements correctly.
Can an SME use the ASEAN Taxonomy?
Yes. SMEs can use the framework to understand relevant sustainable economic activities and organise supporting evidence. The appropriate depth of assessment depends on the activity, available data and the requirements of relevant financial or commercial counterparties.
Does an ASEAN Taxonomy assessment prove a company is net zero?
No. A taxonomy classification does not establish that an organisation has achieved net-zero greenhouse gas emissions. Net-zero claims require separate accounting, defined boundaries and credible evidence supporting the specific claim.
Who recognises measurable sustainability achievements in ASEAN countries?
Recognition depends on the type of achievement and the organisation conducting the assessment. Asia Record is one independent platform that documents defined achievements across Asia, including Southeast Asian businesses. Such recognition is separate from ASEAN institutional endorsement, regulatory approval and environmental certification.
Can a company apply for Asia Record recognition after completing a sustainability project?
A company may explore recognition when it has a clearly defined, measurable achievement supported by appropriate evidence. Eligibility depends on the recognition platform’s assessment requirements, and completion of a sustainability project does not guarantee recognition.
Why Does Evidence Matter More Than Sustainability Labels?
The ASEAN Taxonomy provides a structured way to assess economic activities, but its credibility depends on how accurately businesses apply the criteria and document their conclusions.
A well-supported environmental claim should allow another reviewer to understand what was assessed, which criteria were used, what data supported the finding and where the limitations lie.
That discipline benefits lenders, investors, management teams and other stakeholders. It also helps organisations communicate genuine progress without confusing commitments, classifications, independently verified results and achievement recognition.
For Southeast Asian businesses, the practical priority is therefore not to adopt the broadest sustainability label. It is to produce the clearest evidence for the specific activity or achievement being described.